Tow Truck Financing
Tow truck financing lets you put a rollback or wrecker on the road and pay for it over time: a third-party lender pays the seller, and your business repays on agreed terms. Send the truck details, and Ironmark follows up personally and connects you with a financing specialist.
- Rollback and flatbed car carriers
- Light, medium and heavy wreckers
- Rotators for heavy recovery work
- Self-loaders, wheel-lifts and repo trucks
Get a Quick Quote
Tell us about the equipment. A real person follows up with options.
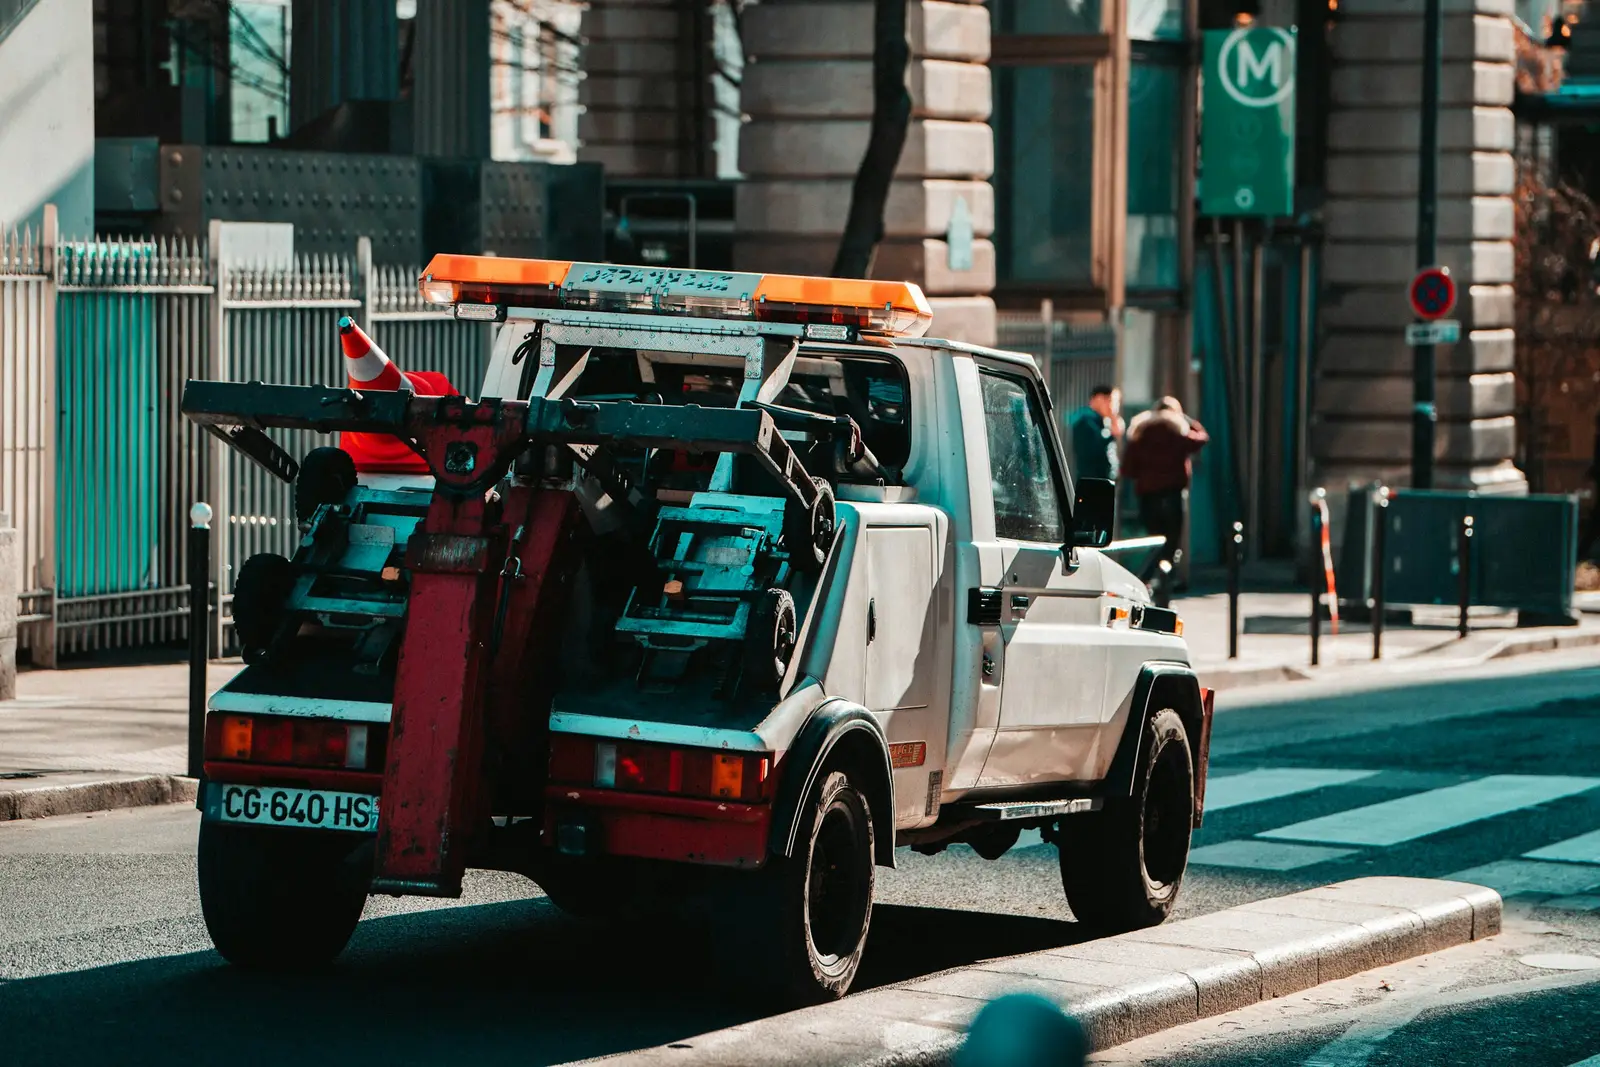
How does tow truck financing work?
Tow truck financing works like most equipment financing. You choose the truck and get a written quote or listing that covers the chassis, the body and the equipment included. A financing specialist reviews your business and the equipment and explains the options, which can include an equipment loan or a lease. If a third-party lender approves the request, it pays the seller and your business makes payments over the agreed term, with the equipment typically serving as collateral.
Many owners finance so cash stays available for fuel, insurance, drivers and storage lot costs. Financing also makes it practical to buy the right truck for the work instead of stretching an undersized unit. Lenders generally view tow trucks as working equipment with an established resale market, and they review the chassis and body of a used truck closely. Terms vary by lender and deal, and every request is subject to approval.
A useful quote covers the chassis year, make, model and miles, the body or wrecker unit's make, model and rating, and whether the truck is new, used or a remount on a newer chassis. Who is selling it and what the price includes, such as lighting, toolboxes or an underlift, matter too. Send those details through the Quick Quote and Ironmark will follow up personally and connect you with a third-party financing specialist.
What you can finance
New and used units from dealers, auctions and private sellers, depending on the lender.
Rollback carriers
Flatbed car carriers with tilting or sliding decks for light-duty towing, dealer transport and accident scenes.
Light-duty wreckers
Wheel-lift and boom trucks built for passenger cars and light trucks.
Medium-duty wreckers
Wreckers built for box trucks, vans, small buses and other mid-weight vehicles.
Heavy wreckers
Heavy-duty units with integrated underlifts for semis, buses and large commercial vehicles.
Rotators
Rotating boom recovery units used for rollovers, heavy recovery and complex scenes.
Self-loaders and wheel-lift trucks
Trucks with integrated wheel-lifts built for quick hookups by a single operator.
Repo trucks
Pickup-based and light-duty trucks set up for repossession work, often with a hidden or self-loading wheel-lift.
Remounts and used tow trucks
Used trucks and wrecker bodies moved onto newer chassis, with records for both the body and the chassis.
Businesses we work with
- Towing and roadside service companies
- Heavy recovery operators
- Repossession agencies
- Auto dealers and vehicle transporters
- Body shops and auto repair
- Salvage and auction yards
- Parking enforcement companies
What lenders look at
Every lender has its own criteria. These are the things that commonly shape the options for this equipment.
Time in business and towing experience
Lenders commonly look at how long the company has operated and the owner's background in towing. Motor club, police rotation or commercial accounts can help show steady work.
Credit and financial history
Personal and business credit history are typically reviewed. Heavier units such as rotators may call for bank statements, tax returns or financial statements.
Chassis age, miles and body condition
For a used truck, lenders weigh the chassis year and miles along with the condition of the bed, boom, winches and hydraulics. Remounts are usually reviewed on both the chassis and the body.
Who is selling the truck
Dealer, auction and private-party sales are handled differently. Private purchases may require title verification and a lien search, and out-of-state trucks may need extra paperwork.
What the price includes
Lenders want to know whether the price covers the body, underlift, lighting, toolboxes and any upfit work. An itemized quote from the seller or upfitter keeps the request clear.
Financing is provided by third-party lenders, subject to their review and approval. Ironmark is not a lender.
Before you apply
- 1Get the chassis year and miles and the body or wrecker unit's make, model and rating in writing.
- 2Ask when the winch cables, hydraulic hoses and cylinders were last replaced or serviced.
- 3If the truck is a remount, confirm the year of both the chassis and the body.
- 4Confirm the truck's weight rating and whether your drivers will need a CDL to operate it.
- 5List the lighting, toolboxes, dollies and other gear you expect with the truck on the written quote.
 Buying guideTow trucks buying guide and inspection checklistWhat to compare, what to ask the seller and a checklist to take to the lot.Read the guide
Tow Truck Financing FAQs
Can you finance a used tow truck?
Yes, used rollbacks, wreckers and repo trucks are commonly financed. Lenders tend to look at the chassis year and miles, the condition of the body and hydraulics, and service history. Whether a specific truck qualifies depends on the lender and the deal.
What credit score do you need to finance a tow truck?
There is no single minimum. Each lender sets its own requirements and weighs credit together with time in business, cash flow, towing experience and the truck itself. Owners with bad credit can still request a quote, but approval is never guaranteed. A specialist can explain which options may fit.
How long can you finance a tow truck?
Terms are set by the lender and depend on the truck's age and condition, the amount financed and your business profile. A lender may offer a shorter term on older used equipment than on a newer unit. Ask the financing specialist to explain the term, payment and total cost for your specific truck.
Can you lease a tow truck?
Leasing is one of the structures lenders may offer for tow trucks, alongside equipment loans, and some leases end with an option to buy the truck. Compare the total cost and what happens when the term ends before you choose. Your accountant can explain how each structure affects your taxes.
Can you get tow truck financing for a new business?
Newer towing businesses can request a quote. Lenders commonly weigh the owner's towing experience, credit history and any motor club, police rotation or commercial accounts, and requirements for startups vary by lender. Financing is provided by third-party lenders, not Ironmark.
Ready to talk about your equipment?
Send a Quick Quote with the equipment and approximate cost. A real person follows up with your options.